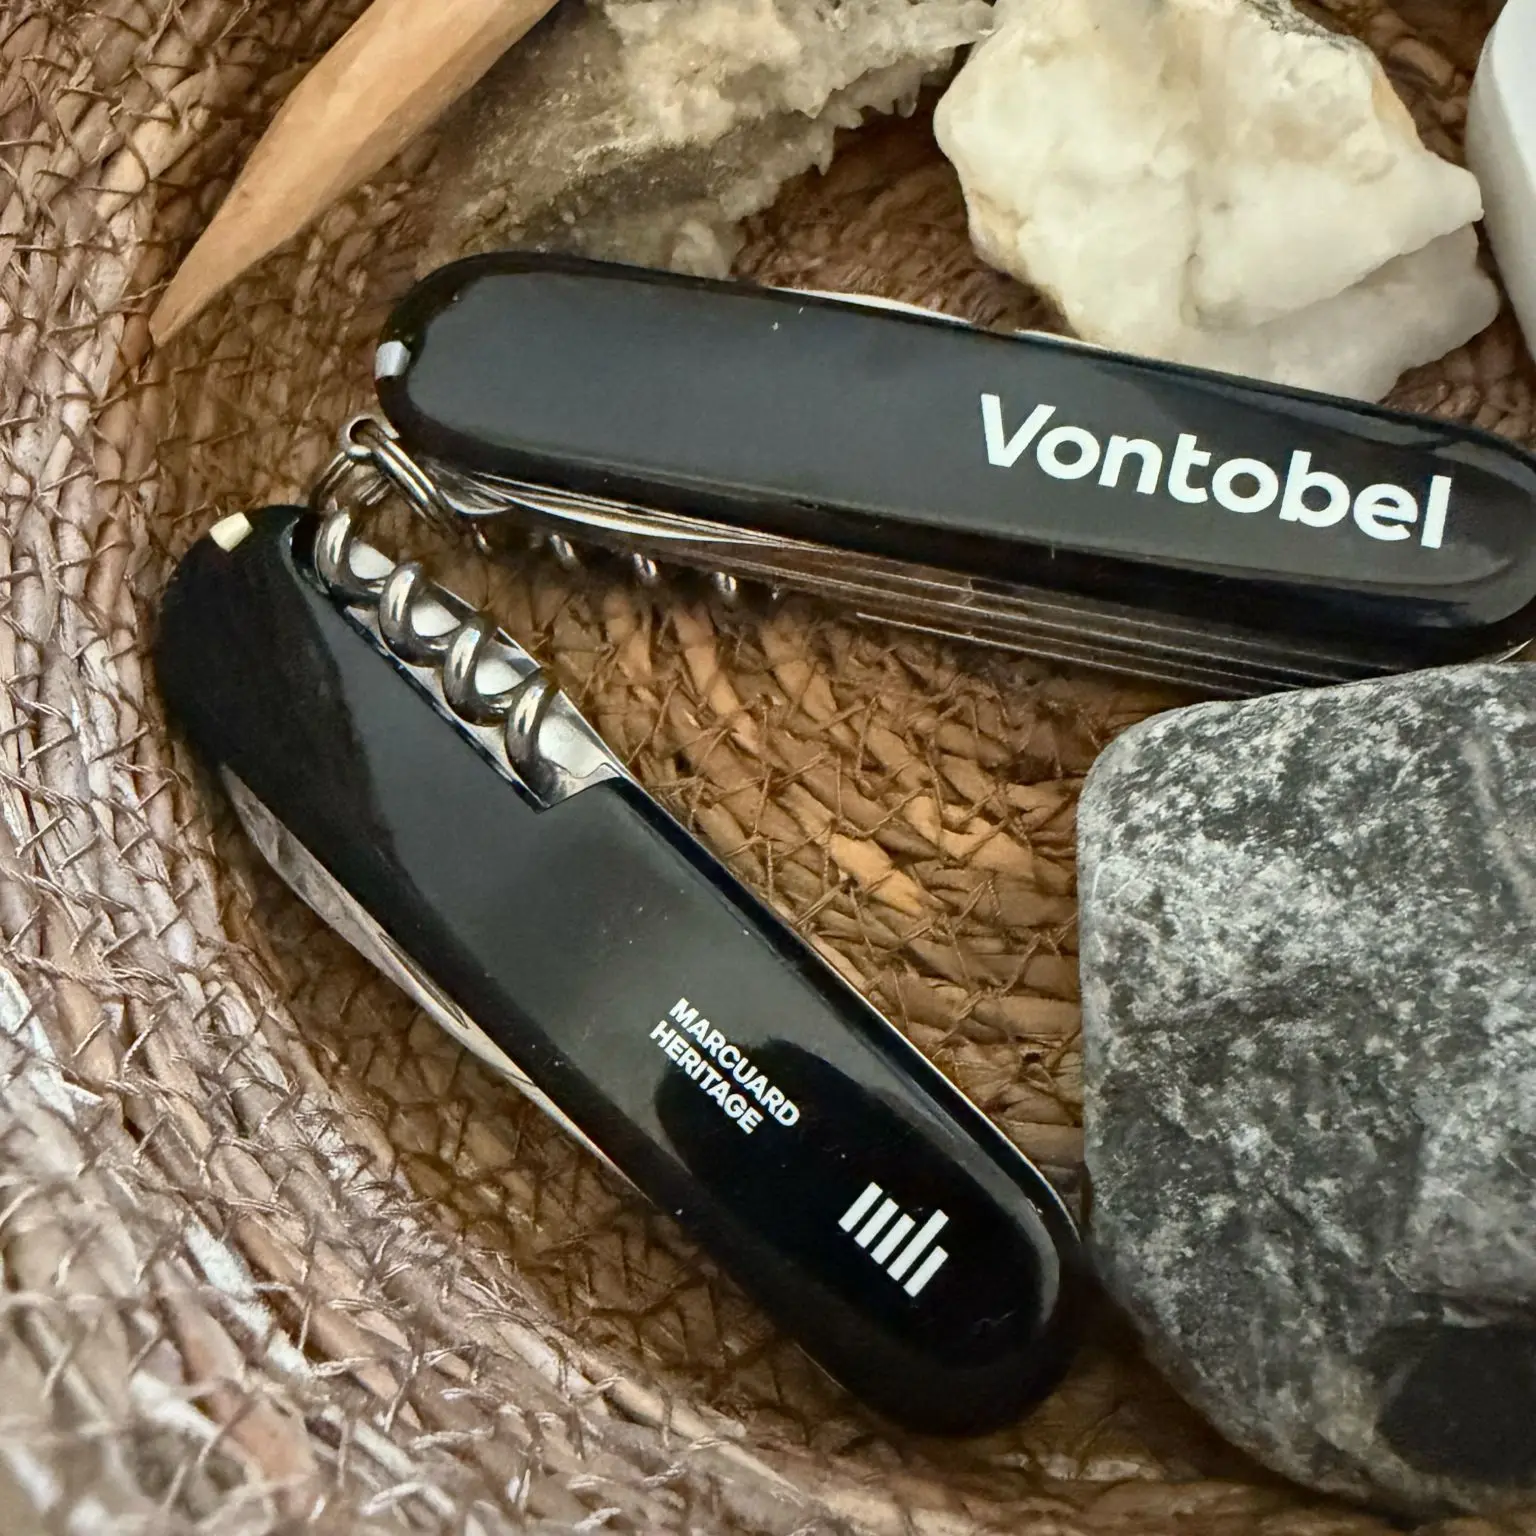
Bank or independent wealth manager? In my experience, the strongest Swiss setups use both. The two Swiss Army knives in the basket by my door carry different logos. Over dinner in Crans last month, a friend picked them both up and asked which one I would actually use.
One carries a bank’s name. The other carries ours. He expected me to defend my own, and I understood why — in Switzerland, the discussion is still often framed as a choice: bank or independent wealth manager. I told him I would keep both, because nobody designed them to replace each other.
Search results decide which firms a wealthy client ever sees: who shows up when a client googles Zurich. Small gestures carry further than most bonuses: what appreciation is worth. Predictability is manufactured, never inherited: predictability as a discipline, not a given. No system survives contact with a real client book: why chasing the perfect system fails.
For many small firms the choice narrows to two options: disappear or merge. Where a firm sits matters less than what that location lets it do: location as a function, not a postcode. Brussels writes rules that Switzerland then has to answer: EU rules and Swiss independence. Being hard to find is not the same as being discreet: invisible does not mean exclusive.
Every structure costs you something you only notice later: what you miss working for someone else. Every machine in this industry traces back to one mathematician: Alan Turing, father of AI. Size changes what a firm can and cannot promise: small, medium or large wealth managers. Consensus is the Swiss operating system, in finance too: Swiss participatory democracy. Reliability is a product, and this country sells it: the train leaves at 07:04. Naming the product in this industry is harder than selling it: what the product actually is. Gold keeps answering a question nobody asked out loud: gold at record highs. The honest answer changes what the job is: who you actually serve. Industry evenings reveal more than the agenda suggests: Swiss excellence on a winter evening.
That answer sounds diplomatic. In practice it is anything but comfortable.
Two roles that were never meant to compete
The custodian bank brings the balance sheet, execution, credit facilities and infrastructure. An independent wealth manager brings continuity of advice, coordination across several banking relationships, and a view of the whole family situation rather than a single account. The roles overlap at the edges, and the client is usually the one who discovers where. Not because anyone breaches an agreement — but because the agreements rarely say who picks up the phone first when markets move over a weekend.
How to close the gap between bank and independent wealth manager
Three things prevent that:
- Define in writing who owns the advice and who owns the execution, including who makes the first call.
- Agree how information flows when assets sit with more than one institution, so nobody reconstructs the picture at the worst possible moment.
- Test what happens when people change roles, because a structure should outlive the individuals in it.
For Relationship Managers and Private Bankers, the useful question is not who leads the relationship. It is who the client believes is responsible when something moves quickly.
Where have you seen that gap open — and what closed it?
The two models compared side by side, on costs, custody, supervision and service: private bank or independent wealth manager in Switzerland.
Source: https://vapa.ch/bank-or-independent-wealth-manager/ · vapa.ch