
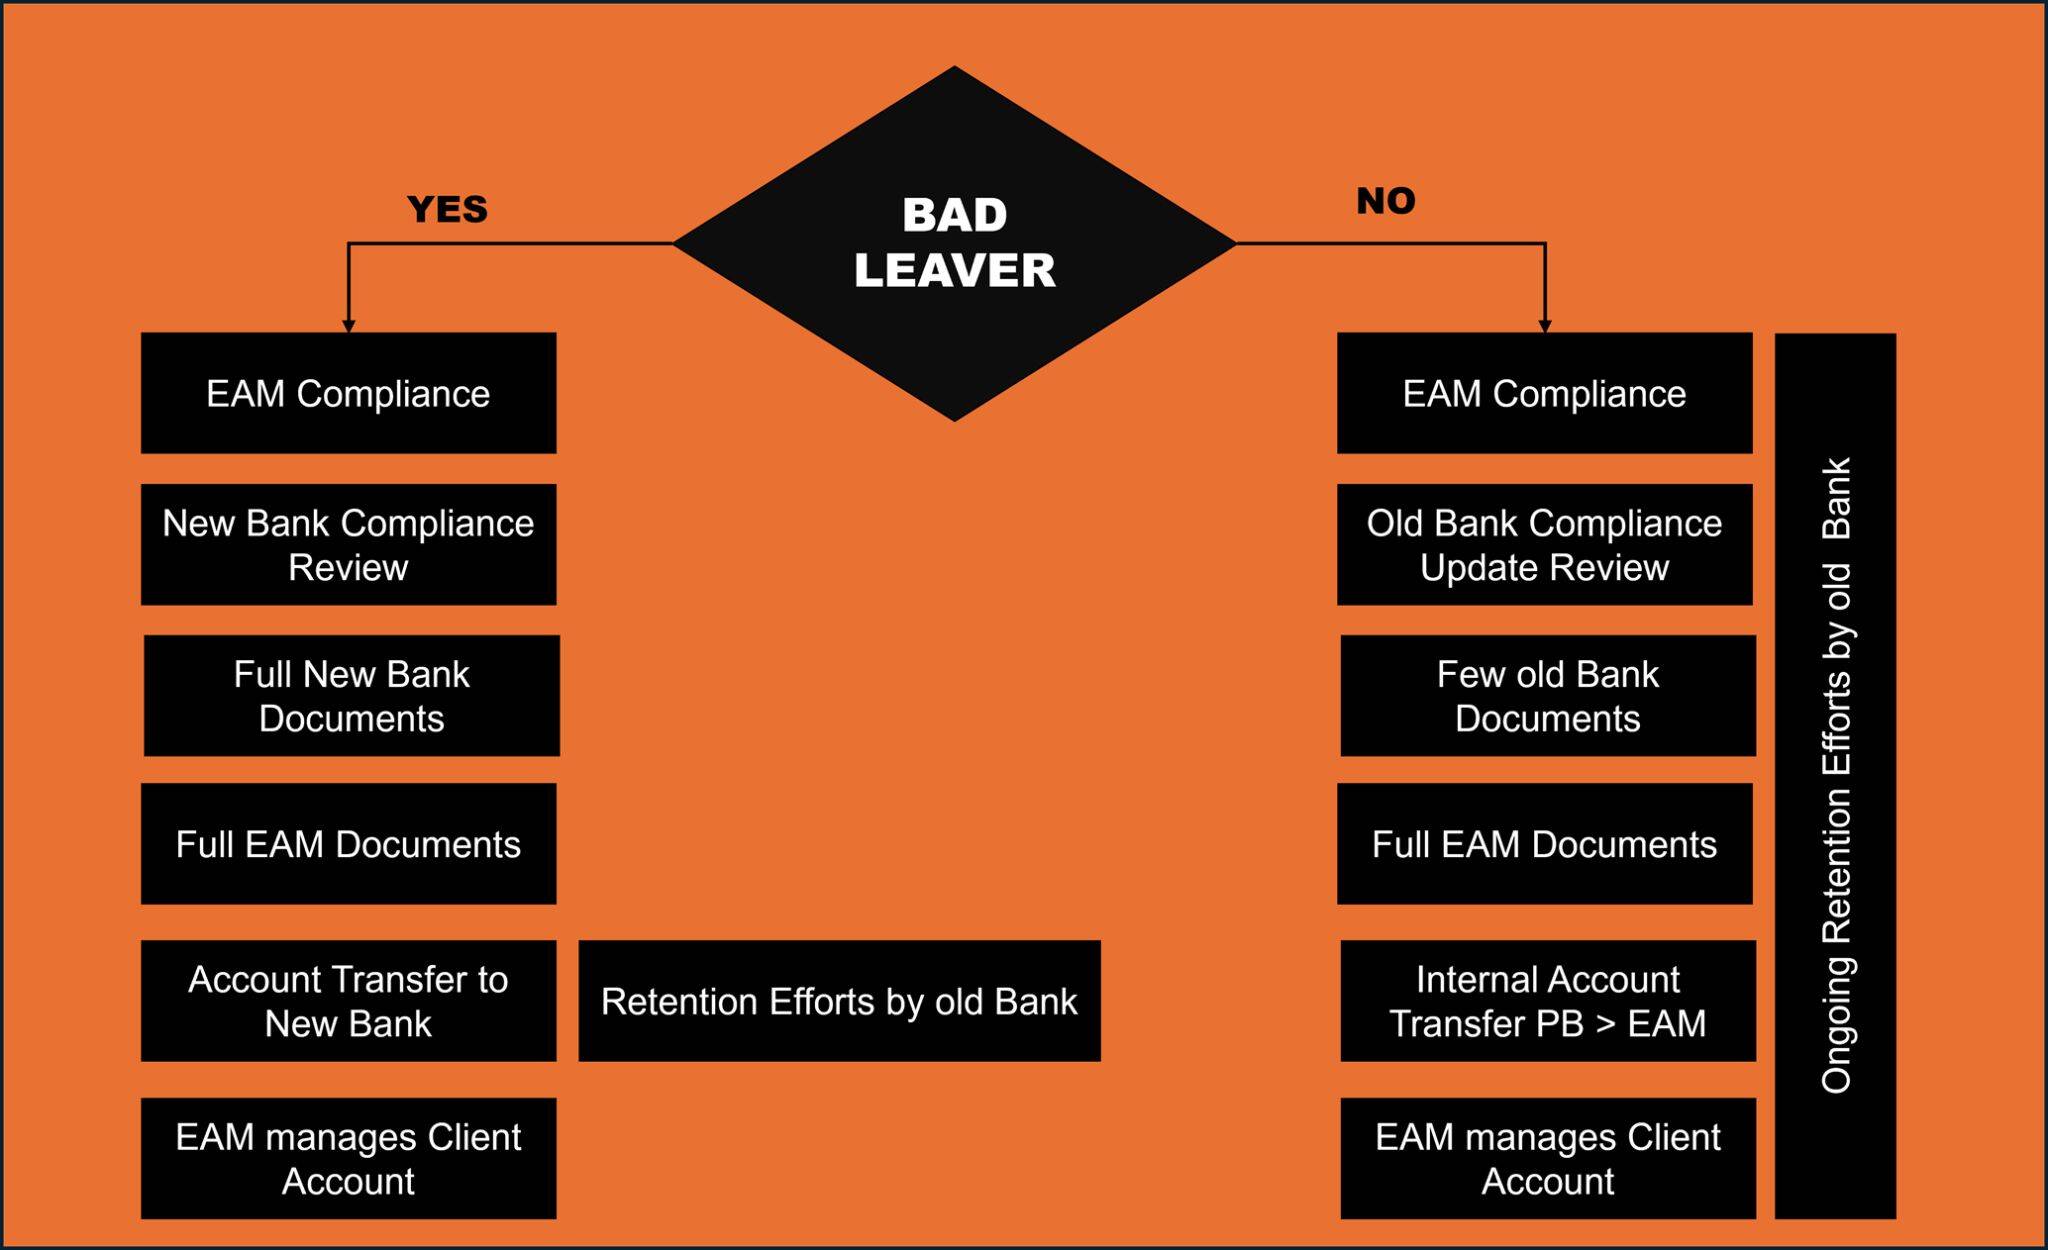
When a Private Banker leaves a bank to join an Independent Wealth Manager, the “Bad Leaver” clause often becomes relevant. Many banks apply this clause verbally, but they enforce it in practice. It blocks the banker from cooperating with the former institution for a defined period. As a result, both the banker and the bank must pause any direct interaction. Even if both sides want to continue the relationship, the rule prevents it. Therefore, the client cannot move directly from the Private Banking division to the same bank’s External Asset Manager (EAM) desk.
However, even though both sides may wish to continue the relationship, the restriction still applies and limits any immediate cooperation.
Yet even without such restrictions, the overall workload of a client transfer remains essentially the same. Every move to an Independent Wealth Manager triggers a full Know Your Customer (KYC) review — a detailed reassessment by compliance, risk, and legal teams. Each client relationship must be revalidated, with documentation, suitability, and risk assessments repeated in full.
The real difference lies in the client’s experience. When the custody account remains at the same bank, the process feels smoother: no new bank documents, no unfamiliar systems, and no need to adapt to new account statements or reporting formats. For the client, this continuity feels seamless — but behind the scenes, the operational and regulatory work continues to be considerable.
For the Independent Wealth Manager and the Relationship Manager, this continuity helps preserve trust and communication. But it does not eliminate the effort required to make the transition compliant and secure.
Ultimately, a “Bad Leaver” status is not the end of the world. It may cause some short-term inconvenience, but it can also mark the start of a new chapter. Building relationships on a clean slate often creates stronger, more sustainable foundations — especially when the old bank actively tries to pull clients back into Private Banking.
This article answers one question: what happens to the client relationships. For what the status is and which clauses create it, see the main article on bad leaver status in Swiss private banking. For what it costs you personally, see what a bad leaver clause actually costs.
Garden leave: where the client relationships are decided
The clause that does the damage is usually not the one anybody argues about. It is the notice period. Advance-notice and garden leave provisions — Freistellung in Swiss practice — keep you employed and paid while releasing you from your duties. You are out of contact with your clients, and your duty of loyalty is still running. The bank, meanwhile, has your client list and sixty to ninety days.
That asymmetry is the point of the arrangement, and it is legal. The practical consequence is that the client relationships are largely decided during a period in which you are contractually unable to participate in it.
What actually transfers
The expectations are consistently too high. Relationship managers expect to keep between a quarter and a half of their client base when they move. A study reconstructing adviser moves from registration filings found that roughly 40 per cent of client assets actually follow. In an average move about a fifth of client money simply stays put.
Timing is unforgiving: most clients who move do so within the first three months, and by month six the outcome is effectively fixed. If you are five months in at 60 per cent, that is the result — not a stage.
The four reasons a client stays behind
- The brand, not you. Some clients were the bank’s clients all along. Tenure with the institution against tenure with you is the honest test.
- Relationship depth. Clients who would describe you as someone they recommend behave very differently from clients who are merely satisfied.
- Legal friction. Non-solicitation stops you reaching out. It does not stop a client acting on their own initiative — but it does mean the first move has to be theirs, and has to be documented as theirs.
- Portability. This is the quiet one. A house fund or a structured product that cannot transfer in kind has to be sold, and a sale creates a tax event. A tax bill is a reason to stay.
What you can do before the notice letter
Nothing in a bad leaver clause prevents a client from choosing where their assets sit. What it prevents is you organising that choice. So the work happens earlier, and it is unglamorous: know which clients are yours rather than the bank’s, know which portfolios can move in kind, know which households have a mortgage or a lombard facility tying them to the building, and make sure that a second person at the new firm is already a name the client recognises.
And be careful with documentation. Where a client approaches you on their own initiative, that history matters later — what counts is the contemporaneous record of how contact began, not a confirmation signed afterwards.
A 40 per cent transfer rate is not a failure. It is the base rate. A plan that only works at 80 per cent is not a plan.
For those who’ve made the move — what was the most surprising part of the transition for you? Let’s share some real-life experiences.
Source: https://vapa.ch/bad-leaver-status-private-banking/ · vapa.ch


